
TL;DR: Saving money on a low income is possible — but it requires a different approach than the standard advice out there. Instead of cutting everything at once, start by finding your “survival number,” stopping the small leaks draining your budget, and automating even tiny savings so the money moves before you spend it. This post walks you through exactly how to do that, including assistance programs most people don’t know they qualify for.
Here’s something nobody talks about enough: a lot of money-saving advice is written by people who have never had to choose between a bill and groceries.
The classic tips — cut out lattes, max out your 401k, invest the difference — sound great when you have breathing room. But when you’re already stretched thin, that advice can feel tone-deaf at best and discouraging at worst.
If you’re trying to figure out how to save money on a low income, you need a different playbook. Not one built for people with extra money lying around, but one that actually works when there isn’t much margin to begin with.
The good news: it’s not impossible. It just requires starting smarter, not bigger.
Can You Really Save Money on a Low Income?
Yes — but consistency matters more than the amount. Even $5 or $10 a week adds up to $260 to $520 over the course of a year. That’s a real emergency cushion, built from almost nothing.
The problem isn’t that low-income earners can’t save. It’s that most people try to save whatever’s left at the end of the month. And there’s almost never anything left. Spending expands to fill income, every single time. The fix is to flip the order: move something to savings first, then live on what remains.
Right now, consumer prices are around 26% higher than they were in 2019, which means paychecks buy noticeably less than they did just a few years ago. That’s a real headwind. But 27% of Americans having zero savings doesn’t mean saving is impossible. It means most people are trying to do it without a system.
Step 1: Find Your Survival Number
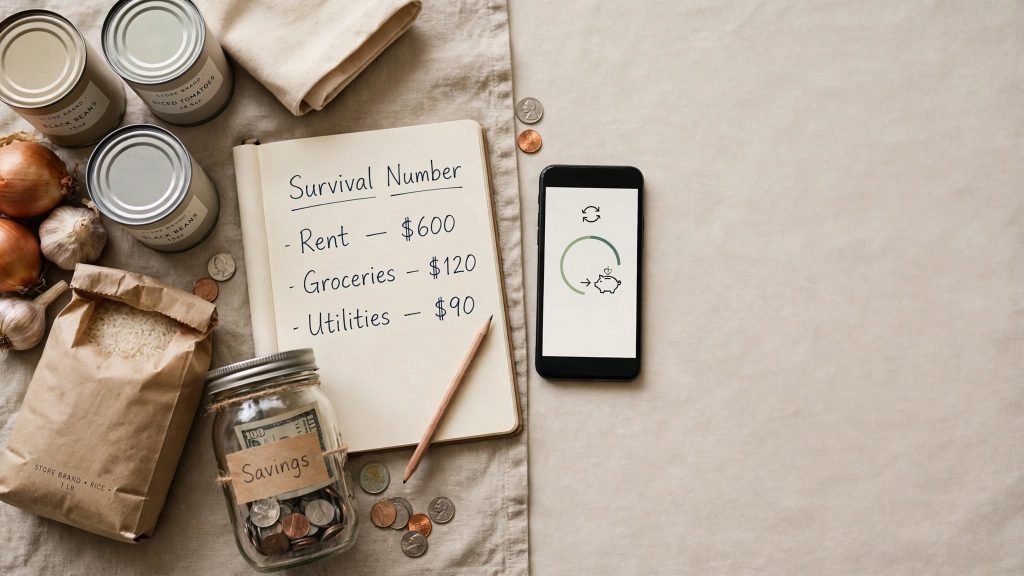
Before you can save anything, you need to know your baseline. Your survival number is the bare minimum you need each month to keep the lights on and food on the table. Nothing else — just the essentials.
Add up these costs only:
- Rent or mortgage
- Utilities (electric, gas, water)
- Groceries (not restaurants — just food at home)
- Transportation to work
- Any medications or essential health costs
- Minimum debt payments
That total is your survival number. Whatever income you bring in above that number — even if it’s just $20 or $30 — is your opportunity money. That’s what you work with. It’s not a lot, but it’s something. And something is where you start.
The popular 50/30/20 rule (50% to needs, 30% to wants, 20% to savings) breaks down fast on a low income, where rent alone can eat 45 to 55% of take-home pay. Even saving just 5% — around $70 a month on a modest income — produces $840 over the course of a year. That’s enough to cover a car repair or an unexpected medical bill without going into debt.
Step 2: Stop the Small Leaks First
Small, forgotten expenses drain low-income budgets faster than any single big purchase. Subscriptions, app charges, and auto-renewals are the biggest culprits. A $6.99 app here, a $12.99 streaming service there — they’re easy to ignore individually, but they add up to real money every month.
Here’s how to find them fast: pull up your last month of bank or credit card statements and go line by line. Look specifically for anything that charged you automatically. Cancel anything you didn’t use or didn’t even remember subscribing to.
Two other quick wins that cost zero effort:
Call your cell phone provider. Ask specifically for their “loyalty rate” or say you’re thinking about switching. The success rate on getting a lower bill this way is over 50%. You’re not being pushy — you’re just asking. Companies would rather give you a discount than lose you.
Check Benefits.gov. A lot of people on low incomes qualify for assistance programs they don’t know about. The Benefits.gov screening tool takes about five minutes and shows you what you may be eligible for based on your household size and income.
Step 3: Automate a Micro-Save on Payday
This is the single most effective move for low-income savers, and it doesn’t require discipline once it’s set up.
On the day you get paid — or the day after — automatically transfer a small amount to a separate savings account. We’re not talking about hundreds of dollars. We’re talking $10, $15, $25. Whatever doesn’t leave you short on essentials.
The key is that it moves before you see it and spend it. Out of sight, out of mind, actually working for you.
Where you keep it matters too. A traditional savings account earns an average of just 0.38% APY according to the FDIC — that’s almost nothing. A high-yield savings account, on the other hand, currently pays up to 4 to 5% APY. On $500 saved, that’s $20 to $25 in interest just for keeping your money in the right place. It’s not life-changing on its own, but every dollar helps when you’re working with a tight budget.
Step 4: Cut Grocery Costs Without Going Hungry
Food is usually one of the biggest controllable expenses in a low-income budget. And there’s real room to reduce it without eating worse.
A few strategies that actually move the needle:
Switch to store brands. Private-label groceries can save you 25 to 30% compared to national brands, and most of them are made in the same facilities. The packaging looks different. The food is usually the same.
Make a list before you shop — and stick to it. Impulse buys are one of the biggest budget killers in the grocery store. A list keeps you focused and cuts down on food waste, which costs the average household of four around $1,500 a year in thrown-away food.
Eat what you have before buying more. Once a month, do a “pantry week” where you cook from what’s already in your fridge and cabinets before restocking. It reduces waste, stretches your budget, and usually leads to some surprisingly creative meals.
Shop at Aldi if there’s one near you. Aldi consistently comes in as one of the lowest-cost grocery options in the country. Their prices on staples like eggs, butter, produce, and canned goods are hard to beat.
Step 5: Check What Assistance You Actually Qualify For
This is the step most people skip — and it can make the biggest difference of all.
There are several federal programs designed specifically to help low-income households, and a lot of people who qualify never apply because they assume they don’t, or they don’t know the programs exist.
Here’s a quick rundown of the main ones:
SNAP (Supplemental Nutrition Assistance Program) helps low-income individuals and families cover grocery costs. Benefits are loaded onto a card you use at the store just like a debit card. You can check eligibility and apply at fns.usda.gov/snap.
WIC (Women, Infants, and Children) provides food assistance, nutrition education, and health referrals for pregnant women, new mothers, and children up to age 5. To qualify for 2025-2026, a family of four needs a household income at or below $59,478. If you already receive SNAP or Medicaid, you automatically meet the income requirements.
LIHEAP (Low Income Home Energy Assistance Program) helps cover home heating and cooling costs. Requirements vary by state, so contact your local LIHEAP office to check availability and eligibility.
211 is a free helpline (just dial 2-1-1) that connects you to local assistance resources for food, rent, utilities, and more. It’s one of the most underused resources out there.
If you’re not sure where to start, BenefitsCheckUp.org screens for all programs at once in about five minutes and is completely free.
What to Do When Things Feel Really Tight
Sometimes it’s not about finding a new strategy. Sometimes you’re just in a genuinely hard spot and need to survive the month.
If that’s where you are right now, focus on three things only:
First, make sure your absolute essentials are covered — housing, utilities, food, transportation. Everything else comes second.
Second, call anyone you owe money to and ask about hardship programs or payment deferrals. Credit card companies, utility providers, and landlords often have options they don’t advertise. You have to ask.
Third, dial 2-1-1. That helpline exists specifically for situations like yours and can connect you to local resources faster than searching online.
You don’t have to solve everything at once. Just get through this month, then work on next month.
Saving money on a low income isn’t easy — but it’s not hopeless either. The difference between people who make progress and people who don’t usually comes down to one thing: having a system, even a small one.
Start with your survival number. Plug the subscription leaks. Move $10 to savings on payday before you touch anything else. Check what assistance programs you qualify for. Swap name brands for store brands at the grocery store.
None of these are magic. But done consistently, they add up to something real. And something real is how you stop living paycheck to paycheck and start building a little breathing room.
You’ve got this. And we’re here to help. Bookmark ClippingDeals.com for more practical money-saving tips, deal alerts, and frugal living strategies — all written for real people on real budgets.
Frequently Asked Questions
How much should I save if I’m on a low income? Start with whatever you can — even $5 or $10 a week is a real start. The goal isn’t a specific percentage at first. It’s building the habit of saving before you spend. Once that’s automatic, you can gradually increase the amount. Even saving 5% of a modest income adds up to several hundred dollars over a year, which is a meaningful emergency cushion.
What is the best way to budget on a low income? Start by finding your “survival number” — the bare minimum you need each month for true essentials like housing, food, utilities, and transportation. Then work with whatever’s left. Traditional budgeting frameworks like the 50/30/20 rule often don’t hold up on a low income, so don’t stress if those don’t fit your situation. What matters is that every dollar has a purpose and your savings move automatically before you have a chance to spend them.
What assistance programs are available for low-income families? The main federal programs are SNAP (food assistance), WIC (nutrition support for women and young children), and LIHEAP (help with energy bills). Many people who qualify for these programs never apply. You can check eligibility for multiple programs at once at BenefitsCheckUp.org, or call 2-1-1 for local resources.
What is the fastest way to save money when you’re broke? The fastest wins usually come from stopping the leaks: canceled forgotten subscriptions, calling your cell provider for a lower rate, and checking whether you qualify for any assistance programs. These three moves cost nothing and can free up meaningful money immediately — no lifestyle changes required.
Is it possible to build an emergency fund on a low income? Yes, though it takes longer. Aim for $1,000 as your first goal — enough to cover most common emergencies without going into debt. Keep that money in a high-yield savings account (currently paying up to 4 to 5% APY) rather than a traditional savings account, where the average rate is around 0.38%. Even small, automatic weekly transfers get you there eventually.